Chapter 2 - The Architecture of a Noose
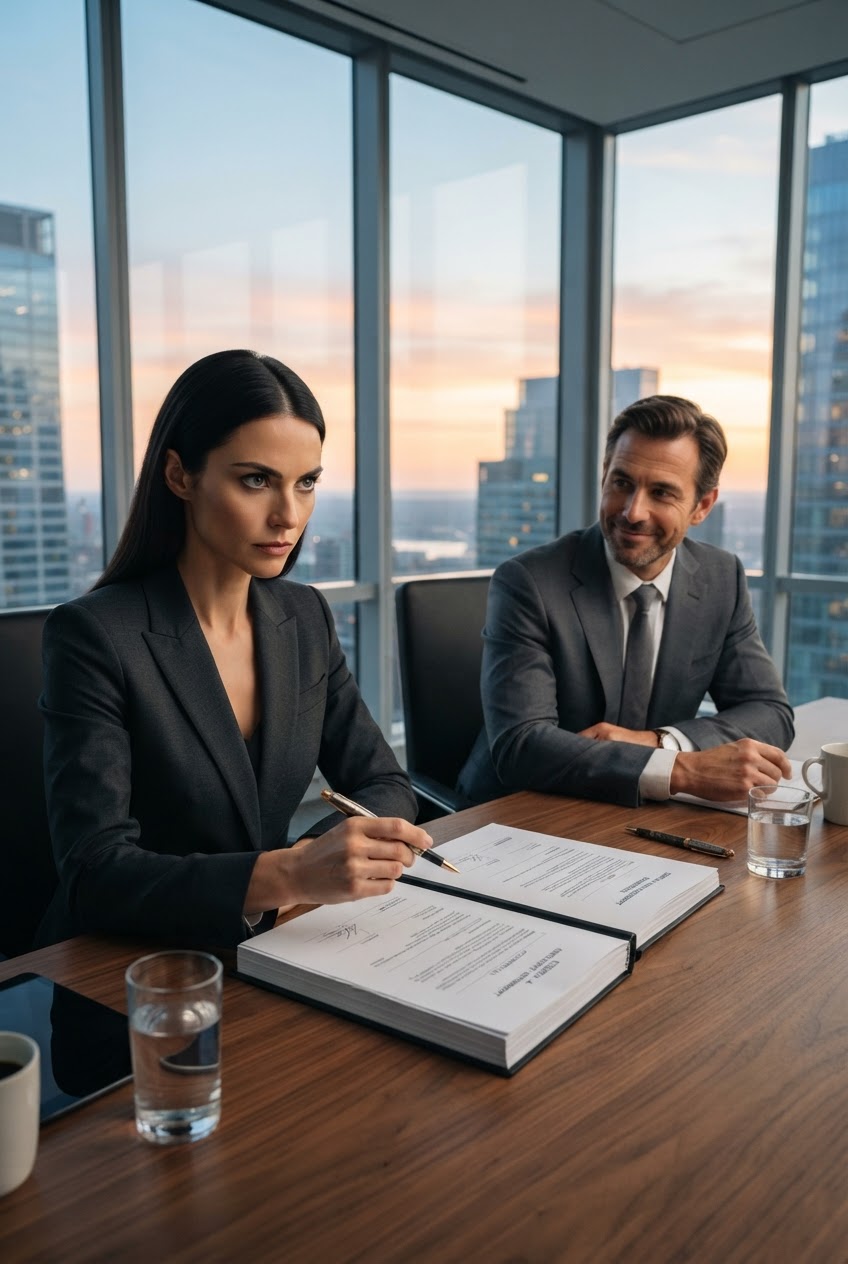
Julian’s smile didn't vanish, but it calcified. It became a ceramic mask, the microscopic crinkles around his eyes flattening out into the sharp, predatory assessment of an executive who had just seen a mouse step around the cheese.
"Leo," Julian said, his chuckle slightly drier this time, carrying the faint, metallic scrape of impatience. "What are you doing, buddy? The wire desk closes the daily liquidity tranche at nine. We went over the high-level deal terms in the restaurant on Sunday. Eight million for thirty percent, five-seat board, standard protective covenants. It’s the exact National Venture Capital Association standard model."
"Then you won't mind if I read the model, Julian," I said.
My voice sounded different. In my first life, my voice in front of venture capitalists had always carried a desperate, eager frequency—the cadence of an ambitious scholarship kid begging the country club gatekeeper to leave the latch undone. Now, it was flat. Cold. Heavy as lead ballast in the hull of a rolling freighter.
I didn't look at him. I pulled a mechanical pencil from my desk drawer, clicked the lead out twice, and smoothed down the first page of the definitive purchase agreement.
Section 1: Authorization and Sale of Series A Preferred Stock.
Outside, the rain slashed harder against the glass, the Chicago wind howling through the concrete canyons of Fulton Market. Across the bullpen, through my office windows, I could see my two co-founders: Marcus, our brilliant infrastructure architect, pacing back and forth with an empty coffee mug; and Maya, our lead cryptographic engineer, staring anxiously at the red monitoring graphs on her dual displays. They knew our AWS bill was past due. They knew we were thirty minutes from oblivion.
They were looking through the glass at me, waiting for the thumbs-up that meant their paychecks wouldn't bounce on Friday.
"Leo, seriously," Julian said, leaning his forearms against the walnut desk, closing the physical distance between us. The scent of his sandalwood cologne was suffocating, masking the smell of stale coffee. "Sarah Vance already had her paralegals skim the draft over the weekend. You’re burning daylight. You want our lead partner to pull the term sheet over procedural paranoia? Because if I pick up my phone and tell the investment committee that the founder is getting cold feet five minutes before the wire, they’ll reallocate this capital to an autonomous logistics deal in Detroit before you finish that cup of coffee."
There it was. The manufactured urgency. The velvet gun to the temple.
"Sarah Vance told me an hour ago that your legal team didn't deliver the final execution annexes until 4:00 AM," I murmured, my eyes tracking line by line through the definitions clause. "Which means Sarah hasn't read the execution annexes. Which means I am reading the execution annexes."
"It's boilerplate, Leo!"
"If it's boilerplate, you have nothing to worry about," I replied, not looking up.
My pencil moved down Page 6.
Section 3.2: Liquidation Preferences.
In the term sheet we had shaken hands on over wagyu steaks at Gibson’s on Sunday night, the liquidation preference was supposed to be a standard 1x non-participating preferred. If the company sold for fifty million dollars, Julian got his eight million back, and the remaining forty-two million was split according to equity percentages. Fair. Clean. Standard market practice for an early-stage Series A.
My pencil stopped at line twenty-four.
“...provided, however, that upon the occurrence of a Deemed Liquidation Event, holders of Series A Preferred Stock shall be entitled to receive an amount equal to three times (3.0x) the Original Issue Price, participating on an as-converted basis with Common Stock in all residual distributions up to an aggregate cap of seventy-five million dollars...”
A 3x participating preference.
My stomach dropped into an icy, bottomless chasm.
If I sold the company for twenty-four million dollars tomorrow, Julian didn't take thirty percent. Julian took twenty-four million dollars. The founders, the common stockholders, the engineers who had slept on office beanbags for eighteen months—we would walk away with zero. Exactly zero dollars.
I didn't yell. I didn't flip the table.
I simply pressed the lead of the mechanical pencil against the margin of line twenty-four and drew a heavy, jagged question mark.
Julian’s eyes tracked the movement of the pencil. The tanned skin over his cheekbones tightened, his jaw muscle pulsing once, twice.
"Typo," Julian said immediately, not missing a beat, his tone smooth as motor oil. "Associate in our drafting pool must have pulled the language from a distressed turnaround template we closed last month in Cleveland. We'll issue a scriveners’ error amendment post-closing. Just initial the tab, Leo. I give you my word as a gentleman, we’ll clean up the paperwork in the thirty-day post-closing clean-up."
I slowly lifted my head, meeting his hazel gaze.
"Your word as a gentleman?" I asked softly.
Julian’s eyes narrowed into slits. The paternal warmth was ninety percent gone now, replaced by the cold, assessing stare of an auditor inspecting a balance sheet for fraud. "You have a problem with my word, Leo?"
"I don't believe in gentlemen in Delaware C-corporation governance, Julian," I said. "I believe in ink."
I turned the page.
Page 14. Section 5: Board Composition and Voting Rights.
In the verbal pitch, Julian promised a founder-friendly board: two seats for the common founders (myself and Marcus), two seats for Apex Vanguard (Julian and an associate), and one independent seat mutually agreed upon by both parties. Balance. Parity.
I read the actual text.
“The Board of Directors shall consist of five (5) members: (i) two (2) designees appointed exclusively by the holders of Series A Preferred Stock; (ii) one (1) designee appointed by the Common Stockholders, who shall initially be the Founder, subject to Section 5.4; and (iii) two (2) Independent Directors, who shall be designated by the Lead Investor, provided that the initial Independent Directors shall be Arthur Vance and Richard Sterling...”
Arthur Vance. Julian’s former business partner at his previous private equity shop. Richard Sterling. The chairman of Apex Vanguard’s institutional LP advisory board.
Julian hadn't built a board. He had built a firing squad.
From Day One, Apex Vanguard wouldn't control forty percent of the board. They would control four out of five seats. Eighty percent. They could convene an unannounced executive session on a Sunday night, declare my management style "unaligned with enterprise growth," vote to strip my title as CEO, and reassign my voting proxy before my Monday morning alarm went off.
"Who picked Arthur and Richard, Julian?" I asked, my voice terrifyingly calm.
Julian didn't answer immediately. He reached into his coat pocket, pulled out his gold-plated phone, and set it on the walnut table with a sharp, deliberate clack. The time on the lock screen read: 8:51 AM.
Nine minutes until the deadline.
"You're acting very strangely, Leo," Julian said, his voice dropping into a low, menacing register that made the hair on the back of my neck stand up. "You look like a man who wants to commit corporate suicide. Do you know what happens at midnight tonight when Amazon pulls the plug on your cluster? Your clients’ data drops off the web. The Chicago Mercantile Exchange cancels your pilot contract for breach of uptime SLA. By Wednesday afternoon, AetherNet isn't a company anymore. It’s an intellectual property bankruptcy auction on the federal court docket."
May you like
He leaned in until his face was six inches from mine.
"You need my eight million dollars, Leo. You need it more than you need your pride. Now stop playing Harvard Law review, pick up that damn pen, and sign the signature page."